FHA Loans in Folsom, CA
Low Down Payment Financing With Flexible Qualification
An FHA loan is a government-insured mortgage designed to make homeownership more accessible for eligible borrowers.
FHA financing may be a good fit if you have limited funds for a down payment, are rebuilding credit, or want more flexible qualification than some conventional mortgage programs provide.
At Rocket Mortgage, eligible borrowers may qualify for an FHA loan with:
As little as 3.5% down
Credit scores starting at 580
Flexible debt-to-income guidelines
Gift funds or eligible down payment assistance
Financing for eligible 1–4 unit primary residences
If you're buying in Folsom, Sacramento, Roseville, Rocklin, Granite Bay, El Dorado Hills, or elsewhere in California, I can help you compare FHA with conventional, VA, jumbo, and other available mortgage options.
What Is an FHA Loan?
An FHA loan is a mortgage insured by the Federal Housing Administration, part of the U.S. Department of Housing and Urban Development.
Because FHA provides mortgage insurance to the lender, FHA loans can offer more flexible qualification standards than some conventional loans.
FHA loans are especially popular with first-time homebuyers, but you do not have to be a first-time buyer to qualify.
The property generally must be used as your primary residence.
2026 FHA Loan Limits in Folsom and Sacramento County
Folsom is located in Sacramento County.
The 2026 FHA loan limits are:
1-unit: $764,7502
2-unit: $979,0003
3-unit: $1,183,4004
4-unit: $1,470,700
FHA loan limits vary by county and property size.
If your required loan amount exceeds the applicable FHA limit, it may make sense to compare conventional or jumbo financing.
FHA Loan Requirements
FHA qualification is based on the complete borrower and property profile.
Credit Score
Rocket Mortgage currently offers FHA financing to eligible borrowers with credit scores of 580 or higher.
Credit history, debt, income, assets, and the overall loan profile are also evaluated during underwriting.
Down Payment
Eligible borrowers may qualify with 3.5% down.
The down payment may come from eligible personal funds, gift funds, or approved down payment assistance, subject to applicable requirements.
Income and Employment
The lender must verify sufficient qualifying income and determine that it is reasonably expected to continue.
Income documentation may include:
Pay stubs and W-2s
Tax returns when required
Self-employment documentation
Retirement or Social Security income
Other eligible income sources
Debt-to-Income Ratio
Your debt-to-income ratio compares your qualifying monthly debt obligations with your gross monthly qualifying income.
FHA underwriting may allow more flexibility than some conventional loan scenarios, but acceptable DTI depends on the complete application and underwriting findings.
Property Requirements
FHA financing is generally intended for a primary residence.
Eligible properties may include:
Single-family homes
FHA-eligible condominiums
Certain manufactured homes
Duplexes
Triplexes
Four-unit properties
For 2–4 unit properties, the borrower must generally occupy one of the units as a primary residence.
FHA Appraisal and Property Standards
An FHA appraisal evaluates both the property's market value and whether the home meets applicable FHA minimum property requirements.
The property must generally provide adequate:
Safety
Security
Structural soundness
Utilities
Heating
Access
Not every cosmetic issue needs to be repaired, but significant health, safety, or structural concerns may need to be corrected before closing.
For homes needing substantial renovation, an FHA 203(k) loan may be worth exploring.
FHA Mortgage Insurance
FHA loans generally require two forms of mortgage insurance:
Upfront Mortgage Insurance Premium
The current FHA Upfront Mortgage Insurance Premium (UFMIP) is generally 1.75% of the base loan amount.
It may typically be financed into the mortgage instead of being paid entirely in cash at closing.
Annual Mortgage Insurance Premium
FHA loans also generally include an annual mortgage insurance premium that is paid monthly.
The amount and duration depend on factors such as:
Loan amount
Loan term
Original loan-to-value ratio
For many FHA borrowers making the minimum 3.5% down payment, annual MIP generally remains for the mortgage term.
Borrowers starting at 90% LTV or lower may generally have annual MIP for 11 years.
Who May Benefit From an FHA Loan?
An FHA loan may be worth considering if you:
Have limited funds available for a down payment
Have a credit score starting around 580
Are a first-time homebuyer
Are a repeat buyer purchasing a primary residence
Need more flexible debt-to-income qualification
Plan to use eligible gift funds or down payment assistance
Want to purchase an owner-occupied 2–4 unit property
The best loan depends on your complete financial situation, not just one qualification factor.
Can You Buy a Duplex or Fourplex With an FHA Loan?
Yes.
FHA financing may be used to purchase an eligible:
Duplex
Triplex
Fourplex
You must generally occupy one unit as your primary residence.
For some borrowers, this can provide a way to purchase a multi-unit property while using eligible rental income from the other units as part of qualification, subject to FHA underwriting requirements.
FHA Loan Process
1. Review your mortgage options
We evaluate your income, credit, assets, debts, down payment, and property goals.
2. Get pre-approved
Your information is reviewed to determine whether FHA or another loan program may fit your scenario.
3. Find a home and make an offer
Once your offer is accepted, the mortgage moves into processing and underwriting.
4. FHA appraisal and underwriting
The property and borrower documentation are reviewed under FHA and lender requirements.
5. Closing
After final approval and completion of required conditions, you review your Closing Disclosure and sign the final loan documents.
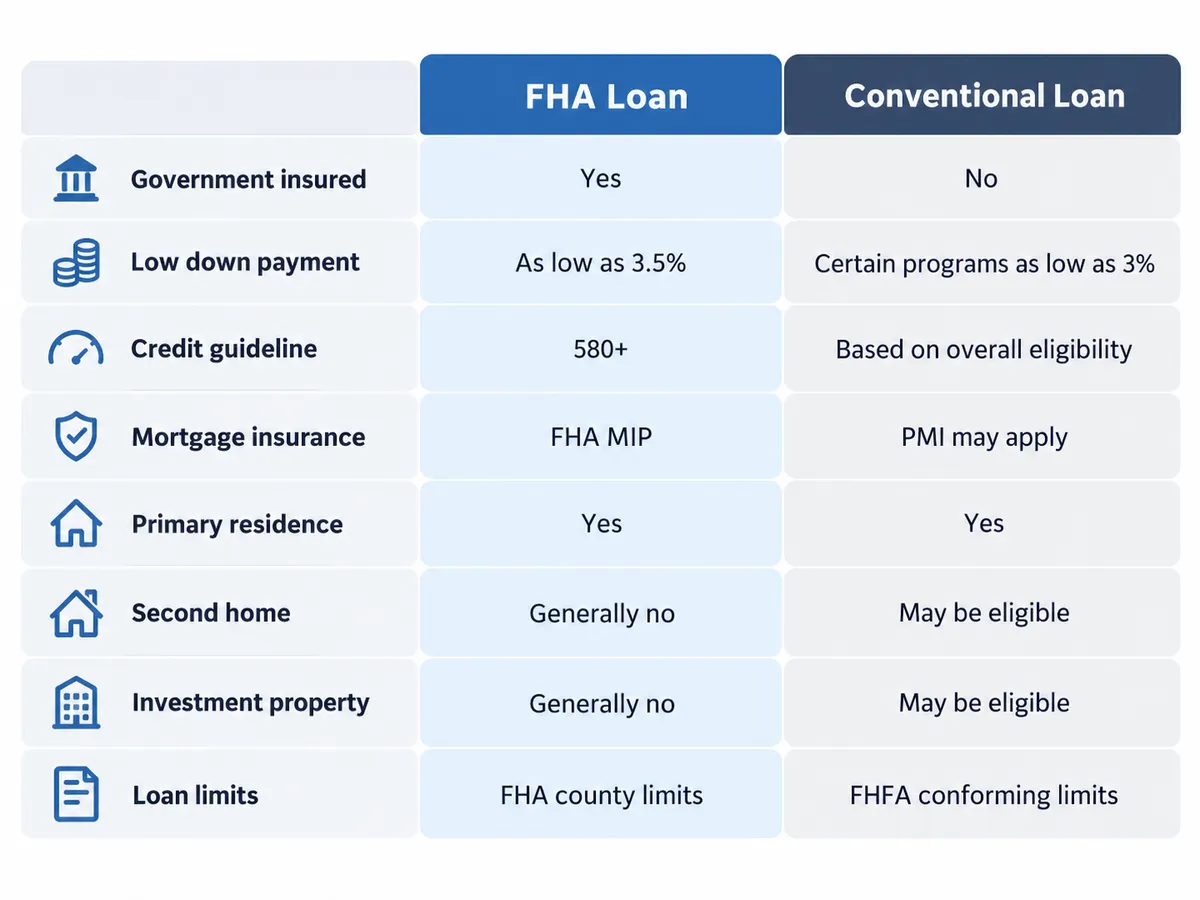
FHA Loans vs. Conventional Loans: Which is Right for You?
Many homebuyers in Folsom weigh the differences between Conventional and FHA loans. Below is a detailed comparison to help you understand why an FHA loan might be the superior choice for your situation.
Why Work With Andrey Dimitrashuk?
Choosing between FHA and conventional financing should involve more than comparing down payments.
I review the complete loan scenario—including credit, income, debts, assets, property, down payment, and long-term goals—to determine which available mortgage option may fit.
Depending on your situation, that may include:
FHA loans
Conventional mortgages
VA loans
Jumbo mortgages
Bank Statement Loans
1099 Income Loans
Asset Depletion Loans
See What My Clients Say
FHA Loans FAQs
Do I have to be a first-time homebuyer to get an FHA loan?
No. FHA loans are popular with first-time buyers, but repeat buyers may also qualify if the transaction meets FHA requirements.
What credit score do I need for an FHA loan?
Rocket Mortgage currently requires a minimum credit score of 580 for eligible FHA financing.
How much down payment do I need for an FHA loan?
Eligible borrowers may qualify with as little as 3.5% down.
Can I use gift funds for an FHA down payment?
Yes. Eligible gift funds may be used for FHA transactions when applicable documentation and program requirements are satisfied.
What is the FHA loan limit in Folsom for 2026?
Folsom is in Sacramento County. The 2026 FHA loan limit for a one-unit property is $764,750.
Can I buy a multi-family property with an FHA loan?
Yes. Eligible 2–4 unit properties may be financed with an FHA loan when the borrower occupies one of the units as a primary residence and other FHA requirements are met.
Does FHA mortgage insurance ever go away?
It depends on the original loan-to-value ratio and loan term. For many borrowers making less than a 10% down payment, annual FHA mortgage insurance generally remains for the mortgage term. With an original LTV of 90% or less, annual MIP may generally end after 11 years.
Can I refinance an FHA loan?
Yes. FHA offers several refinance options, including certain rate-and-term and FHA Streamline refinance programs, subject to eligibility requirements.
Find Out Whether an FHA Loan Fits Your Plans
If you're planning to buy a home in Folsom or elsewhere in California, an FHA loan may provide a flexible path to homeownership.
I can compare FHA financing with conventional, VA, jumbo, and other available mortgage options to help determine which approach may fit your situation.
Andrey Dimitrashuk
Mortgage Loan Originator
Folsom Office
785 Orchard Dr #250
Folsom, CA 95630
Hours: Open 24 hours (by appointment after normal business hours)
Languages: English · Russian · Ukrainian
Языки: Английский · Русский · Украинский
Мови: Англійська · Російська · Українська
Rocket Mortgage is an Equal Housing Lender. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age (provided you have the capacity to enter into a binding contract), because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. The federal agency that administers our compliance with these federal laws is the Federal Trade Commission, Equal Credit Opportunity, Washington, DC, 20580.
California: Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act
© 2026 Loans by Drey, a DBA of Andrey Dimitrashuk operating under Rocket Mortgage. All rights reserved.
Last updated: October 6, 2026