Down Payment Options in 2026: How Much Do You Really Need to Buy a Home?
The 20 Percent Down Payment Myth
If you are planning to buy a home in Folsom, CA or the surrounding areas in 2026, you might be wondering exactly how much cash you need to save. For decades, a stubborn myth has circulated that you must put down 20 percent of the purchase price to buy a house. As a local mortgage expert at Rocket Mortgage, I am here to tell you that this is simply not true.
While a 20 percent down payment does help you avoid Private Mortgage Insurance (PMI) and lowers your monthly payment, waiting to save that much could mean missing out on your dream home. In today's market, there are numerous flexible mortgage programs designed to get you into a home with significantly less cash upfront. Whether you are a first-time homebuyer or looking for an investment property, understanding your options is the first step toward homeownership.
Top Low Down Payment Mortgage Programs for 2026
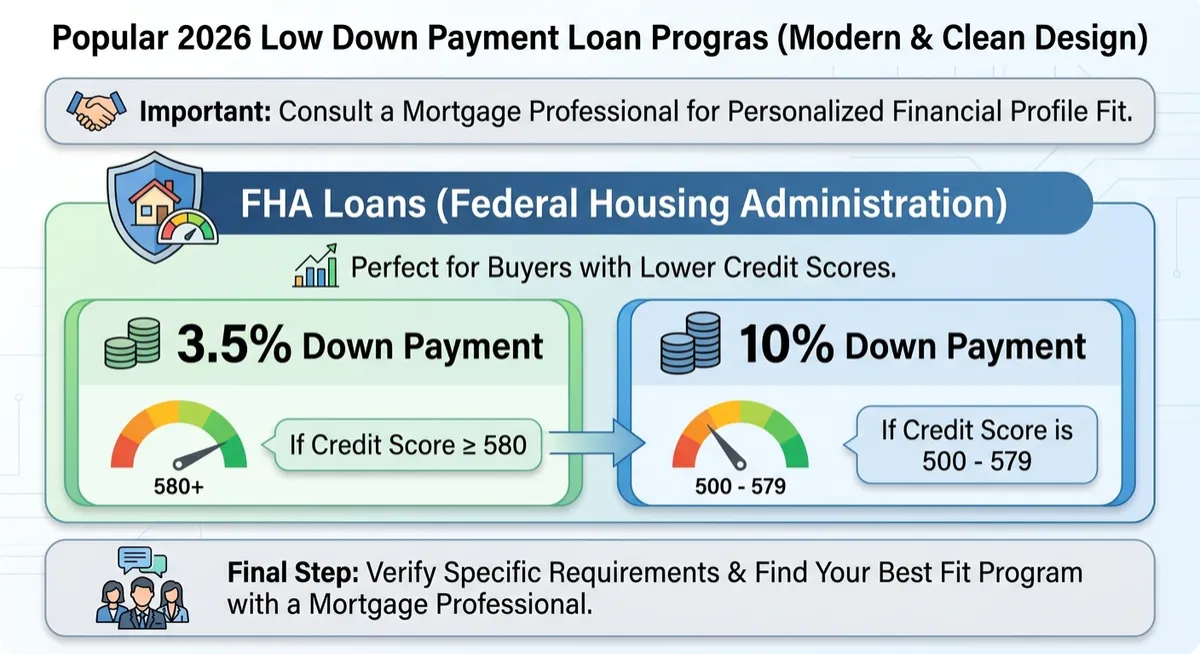
Let us explore the most popular loan programs available in 2026 that offer low down payment options. Each program has specific requirements, so it is crucial to consult with a mortgage professional to see which one fits your financial profile.
FHA Loans: Perfect for buyers with lower credit scores. The Federal Housing Administration requires a minimum down payment of just 3.5 percent if your credit score is 580 or higher. If your score is between 500 and 579, a 10 percent down payment is required.
Conventional Loans: First-time homebuyers can often secure a conventional loan with as little as 3 percent down. Repeat buyers typically need 5 percent.
VA Loans: Available to eligible veterans and active-duty military personnel, VA loans offer incredible benefits, including a 0 percent down payment option and no PMI.
USDA Loans: If you are looking to buy in a designated rural or suburban area, you might qualify for a USDA loan, which also allows for 0 percent down.
These diverse mortgage programs ensure that saving for a down payment does not have to be an insurmountable hurdle.
| Loan Program | Minimum Down Payment | Typical Minimum Credit Score |
|---|---|---|
| VA Loan | 0% | No official minimum |
| USDA Loan | 0% | 640 |
| Conventional (First-Time Buyer) | 3% | 620 |
| FHA Loan | 3.5% | 580 |
| Conventional (Repeat Buyer) | 5% | 620 |
How to Prepare Your Finances for a Home Purchase
Preparing to buy a home involves more than just saving for the down payment. You also need to account for closing costs, property taxes, and homeowners insurance. Here are a few actionable steps you can take today to get ready for a 2026 home purchase:
Check your credit score: Knowing your credit standing helps determine which loan programs you qualify for.
Create a budget: Use a mortgage calculator to estimate your monthly payments and ensure they fit comfortably within your budget.
Get Pre-Approved: A formal pre-approval verifies your income and assets, giving you a clear picture of your purchasing power and showing sellers that you are a serious buyer.
Ready to explore your options? As your dedicated mortgage advisor in Folsom, CA, I am here to guide you through the entire process. Andrey Dimitrashuk, Rocket Mortgage. NMLS# 1583893.
Frequently Asked Questions (FAQ)
What is the difference between pre-qualified and pre-approved?
Pre-qualification is a quick, informal, and often verbal assessment of your financial situation. A pre-approval is a formal process involving verification of your financial information (income and assets) as well as your credit situation. It also involves running your file through an Automated Underwriting System.
How much home can I afford?
Everybody's situation is different. To establish how much of a home you can afford, we need to look into a few key factors: your monthly income, your credit score, how much funds you have saved for a down payment and closing costs, the interest rate, and your current debt situation. It is best to consult with a mortgage professional to properly assess your specific situation.
What should I save for a down payment?
The minimum down payment required for first-time homebuyers is typically 3.5 percent of the purchase price. For repeat buyers, it is between 5 and 20 percent depending on the purpose of the loan. If you want to avoid paying Mortgage Insurance, you would need to put 20 percent down.
What is the lowest credit score required to get a loan?
The lowest credit score needed to buy a house can vary based on the type of mortgage you are applying for. Generally, the minimum credit score for an FHA loan is around 580 to qualify for the low down payment of 3.5 percent. If you have a credit score between 500 and 579, you can still get an FHA loan, but you will need a down payment of at least 10 percent.
Can I use gift funds for my down payment?
Yes, many loan programs allow you to use gift funds from a family member to cover part or all of your down payment. You will need to provide a formal gift letter stating that the money does not need to be repaid. We can help you navigate the specific requirements for using gift funds based on your chosen loan program.
Ready to Take the Next Step?
If you are thinking about buying, refinancing, or simply want to understand your options, the next step starts with a simple conversation.
No pressure. Just clear answers and a plan.
Andrey Dimitrashuk
Mortgage Loan Originator
Hours: Open 24 hours (by appointment after normal business hours)
Languages: English · Russian · Ukrainian
Языки: Английский · Русский · Украинский
Мови: Англійська · Російська · Українська
Rocket Mortgage is an Equal Housing Lender. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age (provided you have the capacity to enter into a binding contract), because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. The federal agency that administers our compliance with these federal laws is the Federal Trade Commission, Equal Credit Opportunity, Washington, DC, 20580.
California: Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act
© 2026 Loans by Drey, a DBA of Andrey Dimitrashuk operating under Rocket Mortgage. All rights reserved.
Last updated: October 6, 2026