Asset Depletion Mortgage Loans in California
Qualify for a Mortgage Using Your Assets
Have substantial savings, investments, or retirement assets—but not enough traditional employment income to qualify for the mortgage you want?
An asset depletion mortgage, sometimes called an asset-based mortgage, allow eligible assets to be used to calculate qualifying monthly income.
This type of financing can be especially useful for retirees, high-net-worth borrowers, investors, business owners, and others whose financial strength is not accurately reflected by W-2 income or tax returns.
What Is an Asset Depletion Mortgage?
An asset depletion mortgage allows a lender to consider eligible assets as a source of qualifying income.
Instead of relying only on salary, wages, or self-employment income, the lender reviews qualifying assets and applies the guidelines of the particular loan program to determine how much monthly income may be recognized.
Depending on the program, eligible assets may include savings, investment accounts, stocks, bonds, money market funds, certificates of deposit, and certain retirement accounts.
The purpose is not simply to show that you have money in the bank. The lender uses an approved calculation to determine whether your assets can help demonstrate your ability to repay the mortgage.
You generally do not need to liquidate all of your assets simply because they are being considered for asset-depletion qualification. Exact requirements vary by program.
Who May Benefit From an Asset Depletion Loan?
Asset depletion financing may be worth exploring if you are:
Retirees and people approaching retirement
High-net-worth borrowers
Investors living primarily from investments
Business owners with substantial assets but limited taxable income
Borrowers with significant assets but irregular traditional income
For the right borrower, asset depletion can provide another way to demonstrate financial capacity without relying exclusively on employment income.
What Assets Can Be Used for an Asset Depletion Mortgage?
The assets that qualify depend on the lender and specific mortgage program.
Common examples may include:
Checking/Savings accounts
Brokerage accounts, Stocks, Bonds, Mutual funds
IRAs, 401(k)s, Other eligible retirement accounts
Not every dollar in an account will necessarily be counted.
Lenders may make adjustments for funds needed for the down payment, closing costs, reserves, taxes, penalties, account accessibility, ownership percentage, or market-value considerations.
That is why the amount shown on an investment statement is not necessarily the same amount that will be used for mortgage qualification.
How Does Asset Depletion Income Work?
Although calculations vary, the basic concept is straightforward.
The lender typically:
Identifies eligible assets.
Applies any required reductions or adjustments.
Subtracts funds that must remain available for the transaction when required.
Determines the amount of assets available for income calculation.
Divides the eligible amount according to the requirements of the mortgage program.
The resulting amount may be treated as qualifying monthly income, subject to program guidelines.
Simple Example
Assume a borrower has $1,000,000 in eligible financial assets.
A lender would first determine which assets are eligible and make any required adjustments for closing funds, reserves, penalties, ownership, or program-specific reductions.
The remaining eligible assets would then be divided according to that particular mortgage program's required calculation to determine qualifying monthly income.
The actual calculation varies by loan program, so $1 million in assets will not produce the same qualifying income under every program.
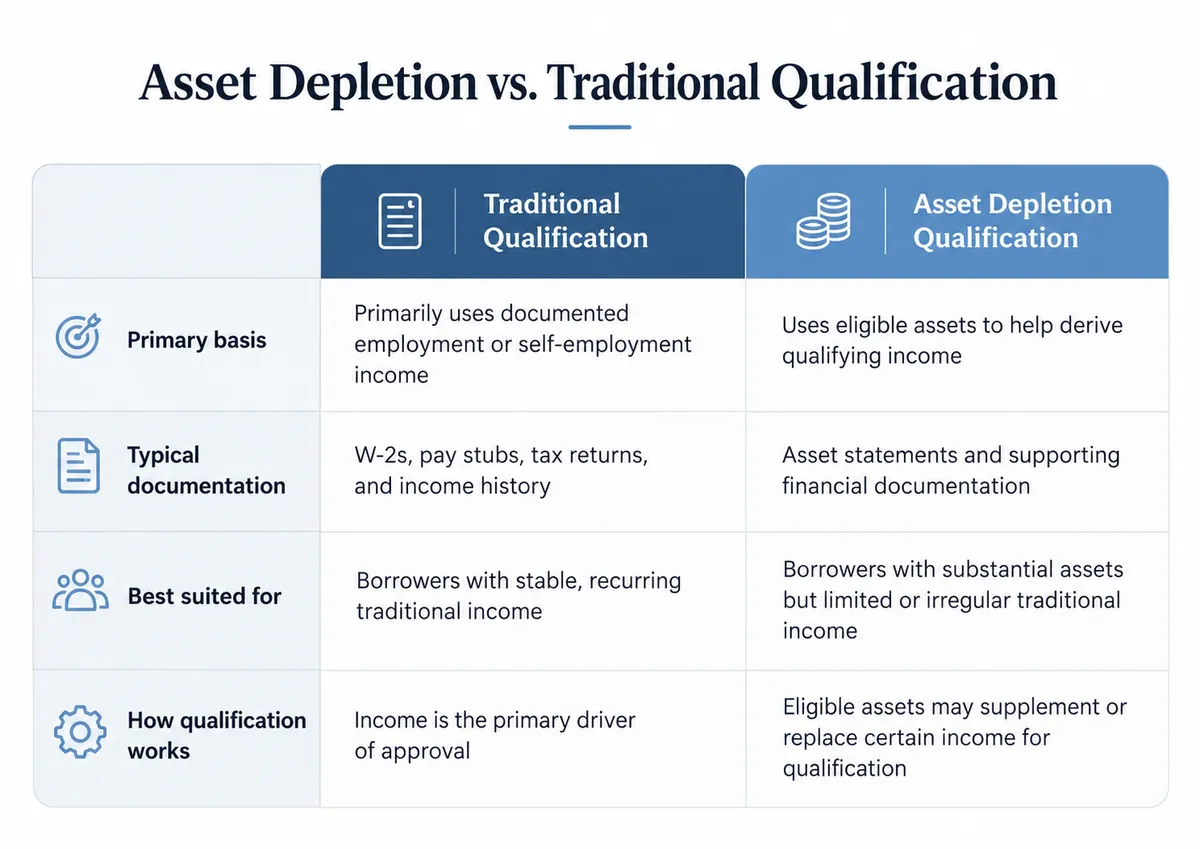
Asset Depletion vs. Traditional Mortgage Qualification
Typical Asset Depletion Mortgage Requirements
Requirements vary between programs, but lenders may evaluate:
Credit profile
Amount and type of eligible assets
Down payment or available equity
Loan-to-value and reserve requirements
Property type and occupancy
Ownership and documentation of assets
Existing monthly obligations and overall ability to repay
Asset depletion does not eliminate mortgage underwriting. It simply provides another method of documenting financial capacity.
Asset Depletion Loans for Retirees
Asset depletion mortgages can be especially useful for retirees whose savings and investments are substantial but whose traditional monthly income is limited. Depending on the program, eligible retirement and investment assets may be converted into qualifying income.
Eligible Social Security, pension, retirement distribution, or investment income may also be considered and, in some cases, combined with asset-depletion income.
Why Choose Andrey Dimitrashuk for Asset Depletion Mortgage Qualification?
Asset depletion scenarios require more than simply looking at an account balance.
Different assets may receive different treatment, and the qualification method can materially affect how much income is available for underwriting.
I help borrowers evaluate the complete financial picture—including assets, income, credit, property, down payment, reserves, and financing goals—to determine which available mortgage option may fit the situation.
If traditional mortgage qualification does not accurately reflect your financial strength, we can explore whether an asset depletion, bank statement, conventional, jumbo, or other available financing strategy makes more sense.
See What My Clients Say
Asset Depletion Mortgage FAQs
Can I qualify for a mortgage using assets instead of employment income?
Potentially. Certain mortgage programs allow eligible assets to be used to calculate qualifying monthly income. Eligibility depends on the type and amount of assets, credit, property, loan structure, and program guidelines.
What assets can be used for an asset depletion mortgage?
Depending on the program, eligible assets may include checking and savings accounts, money market funds, CDs, brokerage accounts, stocks, bonds, mutual funds, and certain retirement accounts.
Can I use a 401(k) or IRA?
Certain retirement accounts may be eligible, subject to program requirements. The amount that can be considered may depend on factors such as accessibility, account ownership, age, taxes, penalties, and other underwriting guidelines.
Do I have to liquidate my investments to qualify?
Not necessarily. Eligible assets may be used to calculate qualifying income without requiring complete liquidation solely for qualification. Funds required for closing or reserves must still meet applicable requirements.
Are asset depletion mortgages only for retirees?
No. Retirees are common candidates, but asset depletion may also benefit investors, business owners, high-net-worth borrowers, and others who have substantial assets but limited or irregular traditional income.
Can an asset depletion loan be used to purchase or refinance a home?
Depending on the available program, asset depletion qualification may be available for purchases and certain refinance transactions. Property, occupancy and loan-purpose restrictions vary.
How much money do I need for an asset depletion mortgage?
There is no single asset amount that applies to every borrower. The amount needed depends on the requested loan, monthly obligations, available income, type of assets, down payment, reserves and the calculation required by the specific mortgage program.
Find Out Whether Asset Depletion Could Work for You
If you have substantial savings, investments, or retirement assets but traditional income documentation is making mortgage qualification difficult, let's review your options.
A short mortgage review can determine whether asset depletion, conventional financing, a jumbo mortgage, a bank statement loan, or another qualification method may better fit your financial situation.
Andrey Dimitrashuk
Mortgage Loan Originator
Folsom Office
785 Orchard Dr #250
Folsom, CA 95630
Hours: Open 24 hours (by appointment after normal business hours)
Languages: English · Russian · Ukrainian
Языки: Английский · Русский · Украинский
Мови: Англійська · Російська · Українська
Rocket Mortgage is an Equal Housing Lender. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age (provided you have the capacity to enter into a binding contract), because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. The federal agency that administers our compliance with these federal laws is the Federal Trade Commission, Equal Credit Opportunity, Washington, DC, 20580.
California: Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act
© 2026 Loans by Drey, a DBA of Andrey Dimitrashuk operating under Rocket Mortgage. All rights reserved.
Last updated: October 6, 2026