Homeowner Equity Insights – Q4 2023
Source: CoreLogic - www.corelogic.com - March 7, 2024
The CoreLogic Homeowner Equity Insights report, is published quarterly with coverage at the national, state and metro level and includes negative equity share and average equity gains. The report features an interactive view of the data using digital maps to examine CoreLogic homeowner equity analysis through the fourth quarter of 2023.
Negative equity, often referred to as being “underwater” or “upside down,” applies to borrowers who owe more on their mortgages than their homes are worth. Negative equity can occur because of a decline in home value, an increase in mortgage debt or both.
This data only includes properties with a mortgage. Non-mortgaged properties (that are owned outright) are not included.
Homeowner Equity Q4 2023
CoreLogic analysis shows U.S. homeowners with mortgages (roughly 62% of all properties*) have seen their equity increase by a total of $1.3 trillion since the fourth quarter of 2022, a gain of 8.6% year over year.
*Homeownership mortgage source: 2016 American Community Survey.
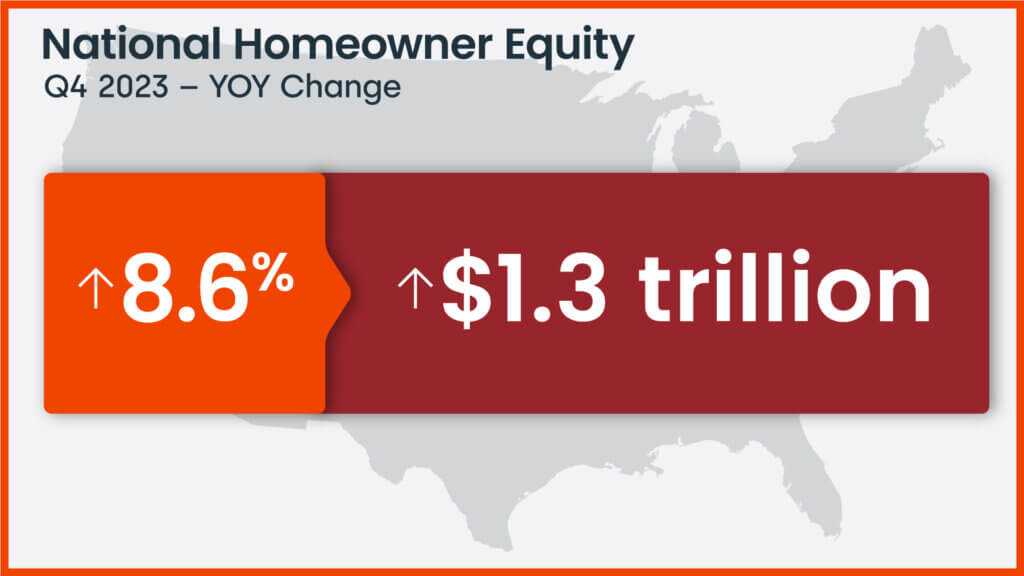
Chart 1: U.S. home equity changes year over year, Q4 2023
In the fourth quarter of 2023, the total number of mortgaged residential properties with negative equity decreased by 1.1% from the third quarter of 2023, representing 1 million homes, or 1.8% of all mortgaged properties. On a year-over-year basis, negative equity declined by 15% to 1.2 million homes, or 2.1% of all mortgaged properties, from the fourth quarter of 2022.
Because home equity is affected by home price changes, borrowers with equity positions near (+/- 5%) the negative equity cutoff are most likely to move out of or into negative equity as prices change, respectively. Looking at the fourth quarter of 2023 book of mortgages, if home prices increase by 5%, 114,000 homes would regain equity; if home prices decline by 5% 162,000 would fall underwater. The CoreLogic HPI Forecast TM projects that home prices will increase by 2.8% from December 2023 to December 2024.
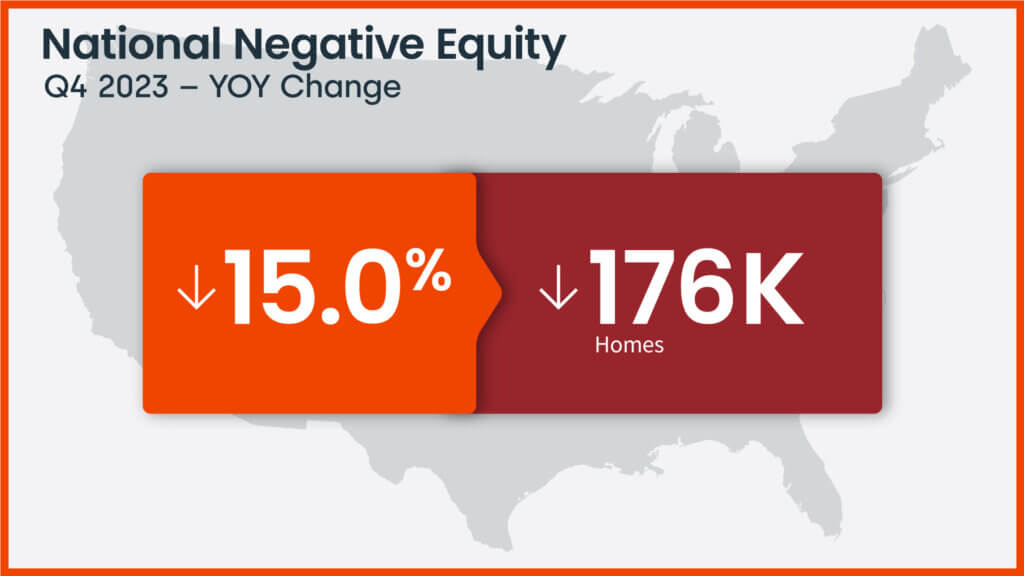
Chart 2: U.S. negative home equity changes year over year, Q4 2023
Northeastern States Lead Annual Home Equity Gains in Q4 2023
Home equity gains continued in the fourth quarter, providing owners with a solid financial cushion, particularly for baby boomers who have been in their homes for a while and thus accumulated substantial equity. Three Northeastern states posted the country’s highest annual equity gains in the fourth quarter: Rhode Island ($62,000), New Jersey ($55,000) and Massachusetts ($53,000). The equity growth in those states is thanks in part to the recent healthy home price increases in that area of the country. According to CoreLogic’s latest Home Price Insights report, Rhode Island and New Jersey led the nation for year-over-year appreciation in January, a respective 13.2% and 11.6%.
National Aggregate Value of Negative Equity: Q4 2023
The national aggregate value of negative equity was approximately $323 billion at the end of the fourth quarter of 2023. This is up quarter over quarter by approximately $9 billion, or 3%, from $314 billion in the third quarter of 2023 and down year over year by approximately $12.4 billion, or 4%, from $336 billion in the fourth quarter of 2022.
Negative equity peaked at 26% of mortgaged residential properties in the fourth quarter of 2009, based on the CoreLogic equity data analysis which began in the third quarter of 2009.
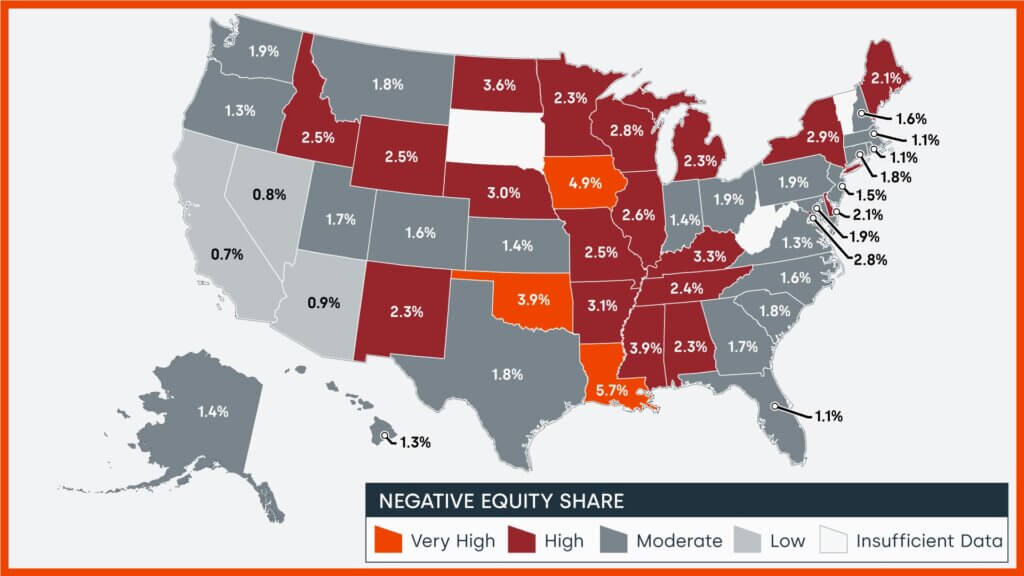
Chart 3: Negative equity share by U.S. state, Q4 2023
“Rising home prices continue to fuel growing home equity, which, at $298,000 per average borrower remained near historic highs at the end of 2023. By extension, at 43%, the average loan-to-value ratio of U.S. borrowers has also remained in line with record lows, which suggests that the typical homeowner has notable home equity reserves that can be tapped if needed. More importantly, home price growth over the last year has helped lift the equity of homeowners who were underwater because of 2022 price declines – meaning that their mortgage amount was higher than the value of their properties. Now, slightly more than 1 million borrowers are underwater, the lowest number recorded in CoreLogic historic data and significantly below the 12 million seen coming out of the Great Recession.”
-Dr. Selma Hepp
Chief Economist for CoreLogic
National Homeowner Equity
In the fourrth quarter of 2023, the average U.S. homeowner gained approximately $24,000 in equity during the past year.
Rhode Island, New Jersey and Massachusetts posted the largest average national equity gains, all at $50,000 or more. Only Texas posted an annual equity loss.
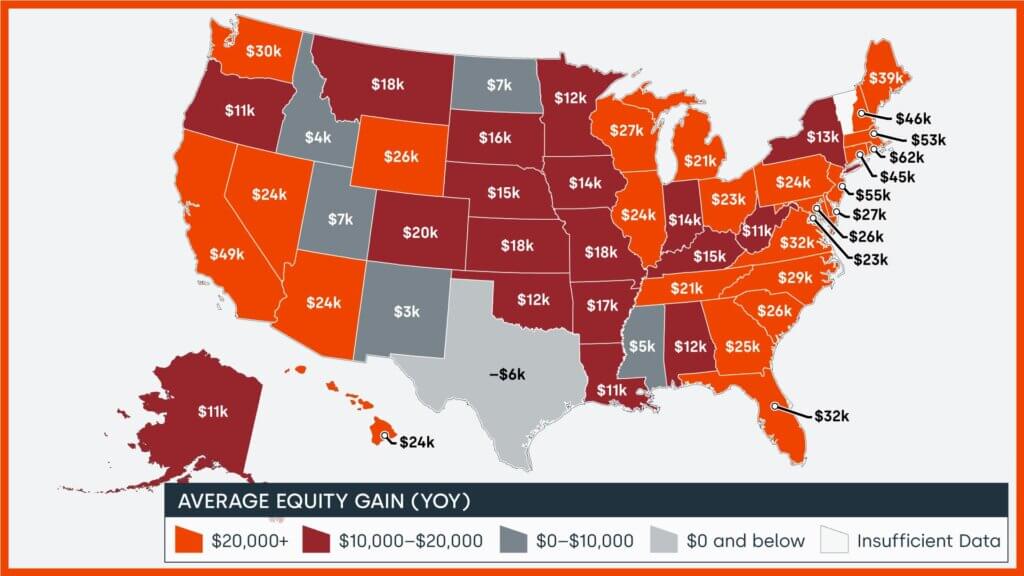
Chart 4: Average home equity changes by U.S. state year over year, Q4 2023
10 Select Metros Change
CoreLogic provides homeowner equity data at the metropolitan level, in this graphic 10 of the largest cities, by housing stock are depicted.
Negative equity has seen a recent decrease across the country. Las Vegas and Los Angeles are the least challenged, both with negative equity shares of all mortgages at 0.7%.
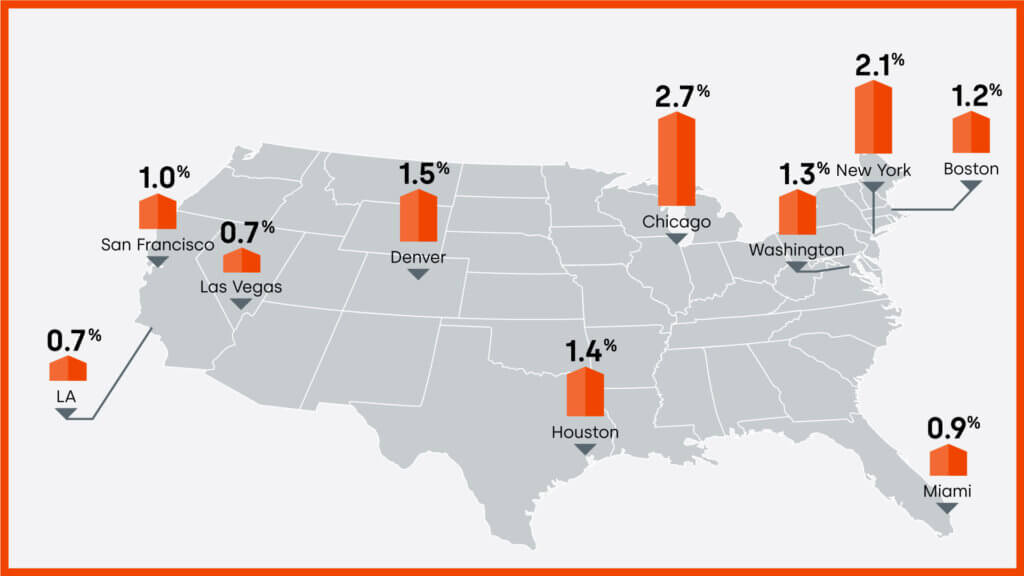
Chart 5: Percentage of homes in negative equity for 10 select U.S. metro areas, Q4 2023
Loan-to-Value Ratio (LTV)
This chart shows national homeowner equity distribution across multiple LTV segments.
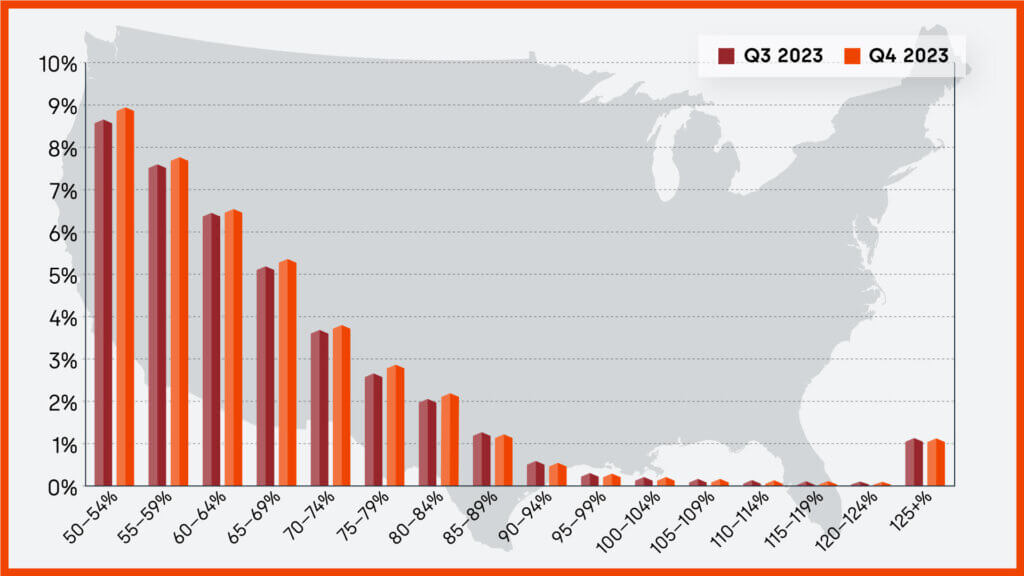
Chart 6: Home equity distribution across multiple LTV segments, Q3 2023 and Q4 2023
Summary
CoreLogic began reporting homeowner equity data in the first quarter of 2010; at that time, the equity picture for homeowners was rather bleak in the United States. Since then, many homes have regained equity and the outstanding balance on the majority of mortgages in this country are now equal to or in a positive position when compared to their loan balance.
CoreLogic will continue to report on homeowner equity as it continues to adjust in communities and states across the country. To learn more about homeowner equity, visit the CoreLogic Intelligence home page.
https://www.corelogic.com/intelligence/homeowner-equity-insights-q4-2023/